Florida Land Residual Analysis: How Operators Price Land
Jacob Sampson
Founding Principal
In Florida land development, the price a disciplined operator can pay for a parcel is not what the seller asks. It is what the math allows after the lots are built, the fees are paid, the timeline is absorbed, and a defensible margin is earned. That math has a name: a land residual analysis.
This is the calculation SIG Fund uses to underwrite every Florida tract we evaluate. It is also the calculation landowners should run before they accept the first offer that crosses their desk, and the calculation accredited investors should look for inside any sponsor's underwriting model.
Below is how the residual works, what each input means in a Florida context, an illustrative worked example, and what a thoughtful reader should look for when reviewing a sponsor's analysis.
What a land residual analysis is
A land residual analysis solves for the price an operator can pay for raw or partially entitled land such that the project still meets its required return after all costs are paid and the finished lots (or finished homes) are sold or transferred at market.
The output is a single number: residual land value. The discipline is in the inputs.
Developers, homebuilders, land bankers, and private real estate fund sponsors all use some version of it. Landowners increasingly use it too, because the math has become harder to hide and easier to challenge.
It matters more in Florida than in most markets because Florida combines unusually rapid demand growth with unusually local cost structures: county-level impact fees, school concurrency, wetlands, FEMA elevation, and a development timeline that can stretch from twelve months to several years depending on the jurisdiction.
The land residual formula
The residual formula in its plainest form:
Residual land value = Finished lot value − Development cost − Soft costs − Required profit − Contingency
Each input is a range, not a number. A real residual model treats it that way. A weak model treats it as a single point and pretends precision it does not have.
The sensitivity of the answer to each input is significant. A ten percent move in lot yield, finished lot price, or development cost can swing the residual by a much larger percentage, because the residual is what is left after the largest items are subtracted.
Inputs in detail
Lot yield
Lot yield is the number of saleable lots per gross acre after losses to allowable zoning, roads, drainage, retention, parks, wetlands, buffers, and any required dedications. Raw acreage rarely converts at one-to-one to gross density.
In Florida, yield loss is often material. A 40-acre tract with a stated zoning density of four units per acre may not produce 160 lots after wet areas, retention, and FDOT off-site requirements are accounted for. The underwriting question is not "what does the entitlement allow" — it is "what can an engineer actually produce within these guidelines."
Finished lot price
Finished lot price is what a homebuilder will pay for a build ready lot (utilities stubbed out and in place ready to connect too) in that submarket on the day the lot is ready to deliver.
Hard costs (horizontal development)
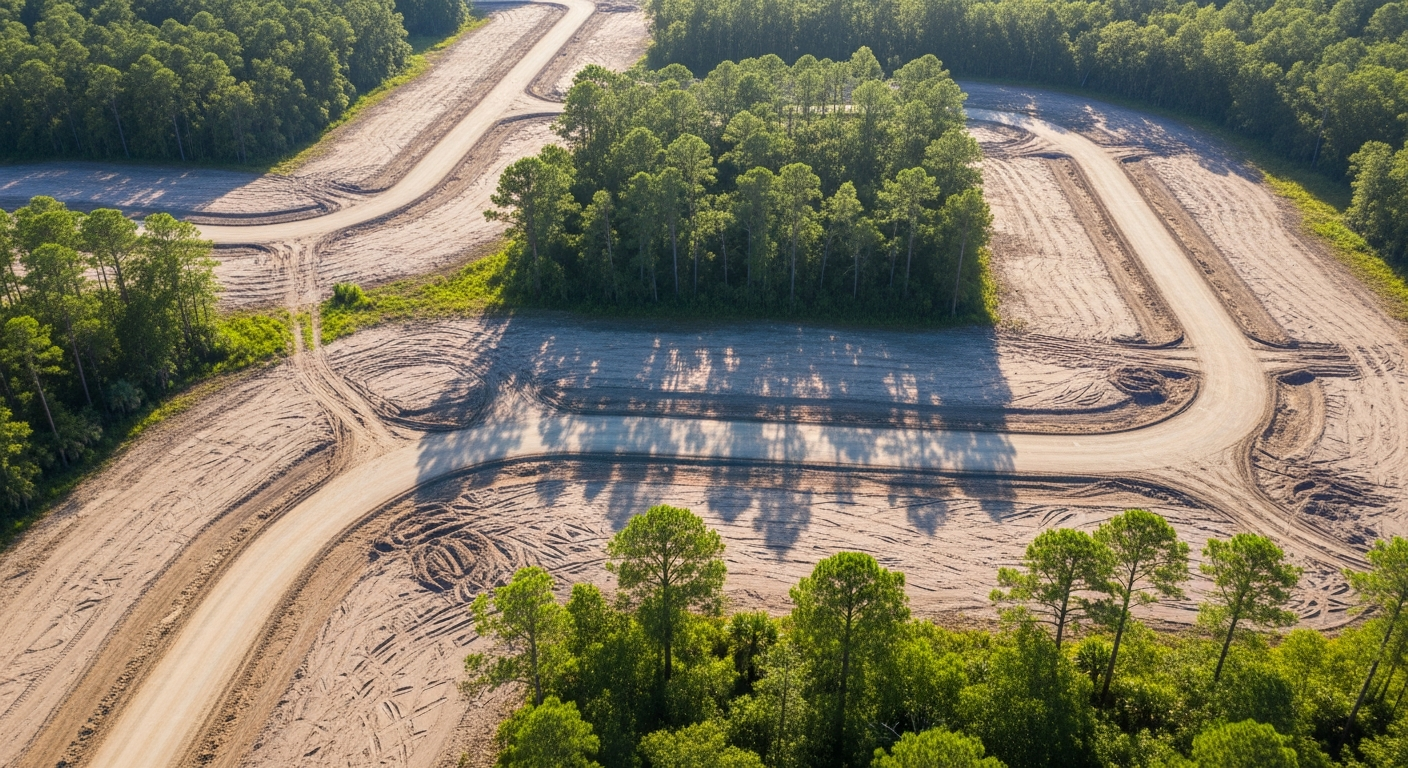
Hard costs cover everything that physically transforms raw land into finished lots: clearing, grubbing, mass grading, stormwater, utilities, roads, sidewalks, lift stations where required, and any off-site improvements demanded by the jurisdiction.
Soft costs
Soft costs cover engineering, surveying, legal, entitlement consulting, environmental, geotechnical, financing fees, project management, and marketing. Soft costs are routinely underestimated by sellers running their own back-of-envelope math.
Profit and return requirement
The required profit is the margin the operator must earn for the project to be worth doing relative to the risk and the cost of capital. It is an input to the residual, not a guaranteed outcome.
In a sponsor's residual model, the required profit is a target the project must clear to be approved. It is not a return the sponsor is promising to investors. Any communication that conflates the two is a communication that should be reviewed closely.
Contingency and time
Contingency is the buffer for cost overruns, regulatory changes, scope additions, and the surprises every horizontal development project produces. Time is the carrying cost of the land and capital from acquisition through entitlement, construction, and disposition.
How builders actually support lot pricing
In practice, land pricing in active builder markets is not negotiated from the land side. It is set by the economics of the finished home.
A majority of builder (including myself) works backward from a target retail price. They know what the home sells for, they know their direct construction cost, they know the margin they need to clear, and they know their soft costs and overhead. What remains is the supportable lot basis — the maximum the builder can pay for a finished lot and still meet their margin on the home.
In most Florida production markets and in my experience all other markets, the supportable lot lands somewhere in the range of twenty to twenty-five percent of the retail home value, with meaningful variation by product type, submarket, and builder. Entry-level product with thin margins and high construction-cost pressure pushes the ratio down. Move-up and premium product with stronger margins can support more. Builders talk in these ratios because that is how they decide whether a submarket is takedown-ready.
The developer sits on the other side of the same equation. The developer's residual land value is what is left after subtracting horizontal development cost, soft costs, impact fees, contingency, and a required development margin from the finished-lot price the builder will pay. If the builder cannot support the finished-lot price the model requires, the developer either finds a different product, a different builder, or a different parcel.
This is the math operators run in their heads before a first meeting. A landowner who understands this conversation can price a disposition. An accredited investor evaluating a sponsor's residual model should expect to see the same logic laid out — finished home value flowing to supportable lot flowing to raw land basis — with every input named and every assumption labeled.
Florida-specific considerations
County impact fees and other hard-dollar costs
Impact fees in Florida are levied by the county and sometimes the municipality, and they vary by jurisdiction, by product type, and by the mix of components each jurisdiction chooses to levy — transportation or mobility, schools, parks, utilities, fire, law enforcement. For underwriting, impact fees live inside the cost stack alongside hard costs, soft costs, and contingency. They are a real number that has to be pulled for each specific parcel and product, but they are not the line that decides whether a deal works. In a finished-home-driven market, what decides a deal is whether the retail home economics support the lot basis the residual requires.
Wet vs dry lots and wetland mitigation
Florida sites frequently include wetlands subject to state and federal jurisdiction. Mitigation banks, on-site mitigation, and avoidance design can change yield, hard costs, and timeline.
School concurrency
Several Florida jurisdictions enforce school concurrency, which can require mitigation payments or, in some cases, hold up approvals when school capacity is at limit.
FDOT access and off-site improvements
Sites on or near a state road frequently trigger Florida Department of Transportation access requirements: turn lanes, deceleration lanes, signalization, or median modifications.
Hurricane, flood, and FEMA factors
Elevation, drainage capacity, base flood elevation, and post-storm regulatory drift all influence cost and sale ability.
Common pricing mistakes operators see
- Pricing land on raw acreage comparables alone.
- Underestimating soft costs and timeline.
- Ignoring what builders will actually pay for the finished lot at retail-driven margins.
- Treating a builder's wholesale lot offer as the residual driver without subtracting the cost to get there.
- Assuming flat market pricing through a multi-year entitlement and construction period.
Raw, entitled, finished: how the residual changes by stage
- Raw land: every input is forward; residual carries the widest range and largest discount for execution risk.
- Entitled land: yield, fees, timeline tighten; residual narrows.
- Finished lots: the calculation collapses toward the builder takedown price minus carrying cost.
How accredited investors should read a sponsor's residual model
A sponsor that shows a residual model with sourced inputs, a sensitivity grid, and explicit assumptions is doing the work to a standard.
Questions worth asking:
- Where do the finished-lot price assumptions come from?
- What lot yield was used, and is it consistent with the current or future zoning use code?
- What county-specific fees were assumed, and when were they last verified?
- What return requirement was used, and how is it framed (target underwriting margin vs. promised investor return)?
- What does the sensitivity grid look like at a 5% and 10% move in price and yield?
If a sponsor's communications convert "target underwriting margin" into "expected investor return" without daylight between the two, that is a communication worth reading carefully. SIG Fund treats those as separate concepts on purpose.
Frequently asked questions
What is the difference between residual land value and appraised value? Appraised value reflects the market for the land in its current condition. Residual value reflects what an operator can pay given a defined development plan, costs, and required profit.
How is lot yield estimated before engineering is complete? Through preliminary site analysis, comparable parcels in the same jurisdiction, and engineering judgment on wet areas, drainage, and dedications.
How do impact fees affect residual value? Impact fees are a real cost in the development stack, pulled parcel-by-parcel for the specific jurisdiction and product type. They reduce residual land value the same way hard costs and soft costs do. In active builder markets, though, what drives residual is the finished home value at retail and the builder's supportable lot — not the fee schedule.
Does residual analysis work for build-to-rent? Yes, with a different finished-product input. Instead of finished-lot price, the analysis solves against the stabilized BTR community value.
How SIG Fund applies this discipline
SIG Fund underwrites Florida land using a residual model with sourced inputs, county-specific fees, engineered yield estimates, sensitivity grids on price and yield, and explicit separation between underwriting margin and investor outcomes.
To read more on how SIG Fund underwrites Florida land, the Insights series is the next stop. If you are an accredited investor and would like to discuss the underwriting framework directly, the For Investors page is the right starting point.